As urban logistics moves closer to the end customer, the industry adapts to new niches.
As far back as the rule of Julius Caesar, urban logistics created the conditions for civilisations to thrive. Dismayed at the state of Rome’s streets, it was he who passed the 44 BC edict Lex Julia Municipalis prohibiting commercial and private wheeled vehicles from navigating downtown during the day – one of the first laws regulating urban logistics.
Ultimately, it did little to abate traffic; last-mile logistics became nocturnal, clogging city streets from sunset to sunrise. Over the succeeding millennia, the wants of our cities have changed dramatically, but their needs have not. In the context of urban logistics, the fast, reliable transport of goods remains its raison d’être, but the industry must now contend with densities, usage requirements and delivery constraints previously unthinkable.
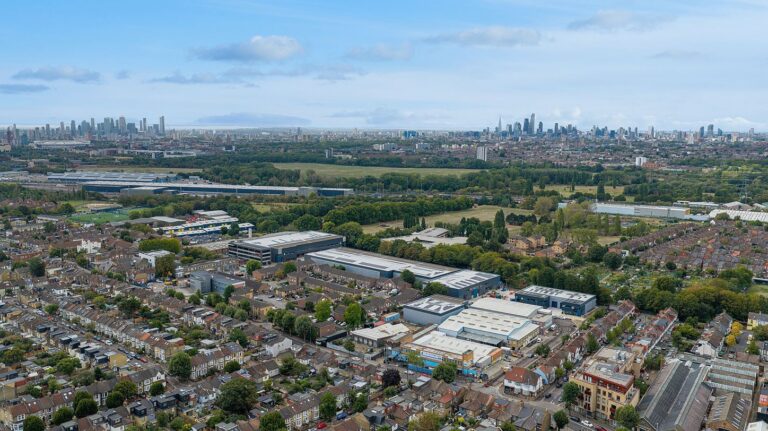
Now one of the financial capitals of the world, London faces similar challenges to the City of Seven Hills that came before it. Restricted by the strict Metropolitan Green Belt, space is at a premium for its urban logistics industry.
High occupancy, changes to residential property regulation and lucrative drop densities across London compound scarcity issues. Savills estimates that the regional development pipeline in London and the South East has fallen by 41%, with 79% of logistics transactions in H1 2026 involving second-hand space. The result is a robust, growing industry foraying into a variety of property formats.
Mile high
Traditional warehouses require large spaces, but micro hubs flip that reasoning on its head. Additionally, advances in automation have enabled greater storage maximisation, increasing the viability of previously unviable property formats.
“Location comes first,” says Mark Symonds, co-founding partner at specialist logistics developer Padrock. “There is no single statutory definition of a micro hub. The closest established London term is TfL’s description of a micro-consolidation centre: a facility much closer to the delivery point, usually serving a smaller area and lighter goods, with onward delivery often by cargo bike or small electric van. We use micro hub in that practical sense, rather than as another name for any small warehouse.”
As a London-based property investment, development and asset management company, Padrock is acutely aware of the demands of London’s logistics providers. As the city continues to deal with space constraints, it is those who can utilise any square footage that stand to benefit.
“A site is commercially viable when the savings it creates downstream are greater than the additional cost and complexity of operating the hub,” explains Finmile co-founder and CEO Rich Pleeth.
“It needs sufficient daily volume to spread the rent, labour and infrastructure costs, while being close enough to delivery demand to reduce mileage and increase the number of stops each vehicle can complete. The building must work operationally, [with] easy loading, enough staging space, charging capacity and quick access to the delivery area.”
FIND OUT MORE: Urban Logistics Exhibition 2027 comes to London Excel 9-10 June
Beginning life as an e-cargo bike delivery company, Finmile spotted a gap in the market, using its vast data set to evolve into the AI-powered logistics execution platform it is today. Growing from 20 parcels a day to 55,000, it built the aggregated data and expertise needed to identify the route ahead for London’s expanding urban logistics industry.
“The most effective sites have ground floor operational spaces located close to dense delivery areas with direct vehicle access, enough room to receive, sort and stage parcels, secure bike storage and the ability to charge vehicles safely,” Pleeth continues. “A site on the edge of a dense zone can offer lower costs and better inbound access while still allowing bikes or vans to reach the delivery area quickly.”
With many transactions increasingly involving second-hand facilities, some developers are considering converting existing properties into vertical warehouses. Heavy-duty lifts bring vehicles directly to operational floors where cube storage systems and automated storage and retrieval systems stack products from compact, high-rack configurations.
“Some buildings can be adapted, but in many cases the opportunity is redevelopment or intensification rather than simple conversion,” says Symonds. “An obsolete single-occupier building can sometimes be replaced by a modern multi-let scheme accommodating more businesses and jobs on the same land.”
For properties built to fit, designs must incorporate flexibility, automation and efficient vertical circulation from the outset, allowing operators to maximise storage capacity while adapting to changing vehicle types, sales models and any operational requirements that crop up.
“Access and loading are not secondary design details; they determine how many vehicle movements can be handled safely and reliably,” Symonds continues.
“Yard depth, turning, gate position, separation of vans and HGVs, on-site waiting and parking all matter. A poorly arranged site pushes vehicles onto the public road and transfers cost and congestion to its neighbours.”
However, high-volume areas are only as good as their distribution points. Any site close to the city centre must be evaluated not just for its location, but also for how that location interacts with a potential customer base.
“A site can look perfect on a map and fail during ops, for example [due to], difficult loading access, insufficient space to sort and stage parcels, vehicles queueing outside, restrictive operating hours, inadequate electrical capacity and conflict with neighbouring residents or businesses,” says Pleeth.
“Often during growth an operator may have insufficient or inconsistent volume, as every hub introduces an additional touchpoint, with parcels unloaded, sorted and loaded again. Unless the hub removes more cost and mileage from the final delivery stage than it adds through rent, labour and handling, it will not work commercially.”
Proximity premium
All businesses prioritise the balance sheet and cheaper locations further out may be tempting, but the efficiency loss from moving away from the customer is a risky proposition.
“Proximity matters because urban logistics supports frequent and often time-critical journeys to shops, hospitals, construction sites, restaurants and homes,” Symonds continues.
“A cheaper building farther out can be more expensive once mileage, driver time, reliability and emissions are counted. Weight, operating-hours and emissions restrictions must therefore be tested against the actual routes and operating day. The catchment should be designed from journey data, not a radius on a map. The best sites are close enough to the customer and connected well enough to serve them without creating a new local problem.”
“Proximity only creates value if the downstream routes are sufficiently dense; a hub that is slightly farther away but consistently full can be more viable than a central site operating at half capacity,” adds Pleeth.
British Land amassed a £1.3 billion urban logistics pipeline over recent years, having identified that occupiers’ need for space was growing faster than the market could handle.
Sensing the shifting trends, property giant LondonMetric Property followed suit, with the urban logistics share of its portfolio jumping from 29% in 2024/25 to 38% in 2025/26. With so many vying for so little space, the time is now for local councils and government – those that would benefit the most – to create a viable framework for urban logistics property development.
FIND OUT MORE: Urban Logistics Exhibition 2027 comes to London Excel 9-10 June
“London needs a joined-up strategy across boroughs rather than a patchwork of different rules. Planning should make it easier to test temporary and flexible logistics uses before operators commit to long leases,” Pleeth concurs. “The city should also identify underused public and commercial sites that could support consolidation, charging and clean final-mile delivery. Loading space and power infrastructure are just as important as the warehouse.”
“The draft London Plan is now out for consultation and separately addresses industrial land and data centres. That is a constructive direction of travel,” Symonds adds.
“London needs consented sites with workable access and credible power delivery dates. It needs both digital and physical infrastructure, but their locational and infrastructure requirements differ. Grid connections should prioritise mature, deliverable projects against published readiness criteria. Developers will succeed where they solve a specific operational shortage in a location where access, yards, power and customer catchment align.”
No matter its effects, if regulation is functional, it can long outlast its implementer. Such was the case with Lex Julia Municipalis, only becoming functionally obsolete in the 3rd century AD. Still, each successive ruler that tried to innovate on Caesar found that they could only amend his rulings. London regulators can only dream of such prescience, but it would be foolish to create policy agendas with only the short-term in mind. Their focus, and indeed that of any logistics developer, should be inscribing their work into the history books through integrated logistics planning.
“Policy should focus on outcomes such as fewer miles, less congestion and lower emissions, rather than assuming that mandating a particular vehicle or building format will produce the right result,” Pleeth concludes. ν
Making space for freight – from urban consolidation hubs and last-mile property to rail, river, kerbside access and cleaner vehicle fleets – will be a central theme at Urban Logistics, taking place at Excel London on 9-10 June 2027.
The event will bring together logistics operators, retailers, property owners and developers, technology and fleet providers, local authorities and policymakers to examine how cities can turn ambitions such as those in the Draft London Plan into workable, commercially viable logistics networks.
Find out more at urbanlogisticsexhibition.com